

Amex

- 15.03K Reviews
- 4.8
- Downloads
- 10,000,000+
Our take on Amex from Appgk
I found Amex most useful when I treated it as a focused companion for managing an American Express account rather than as a complete personal-finance hub. It is a free finance app from American Express, and its main job is straightforward: help me check account information, make payments, and handle rewards without opening a browser every time. That narrow purpose is also its biggest strength. When I need a quick answer about my Amex account, the app gets me there with less effort than a desktop session.
My overall impression is positive, but the experience depends heavily on the account setup and the phone itself. A smooth login makes the app feel quick and practical. A failed sign-in, an interrupted payment, or a screen that does not refresh can make the same app feel confusing because financial tasks require more confidence than ordinary browsing. I would recommend it to existing American Express customers who want mobile access, while people looking for a single dashboard for several banks or cards may prefer a broader money-management tool.
Where the experience usually gets stuck
The first point of friction is often account access. A person may install the app expecting to start immediately, then discover that the important actions depend on successfully signing in to an existing American Express account. I would have my login details ready before beginning, and I would avoid repeatedly guessing credentials if the first attempt fails. In financial apps, repeated failed attempts can create more trouble than taking a moment to check the account information carefully.
Another common source of confusion is the difference between an app problem and an account problem. If the balance looks old, a payment option is unavailable, or rewards do not appear as expected, that does not automatically mean the application is broken. Account status, transaction timing, connectivity, or a temporary service issue can all affect what appears on screen. My habit is to note exactly what is missing and when I last saw the correct information before trying several fixes at once.
Best Parts of Amex
Things to Keep in Mind About Amex
The app is designed around American Express accounts, so its usefulness is naturally limited outside that ecosystem. I would not install it expecting it to replace a general banking app, a budgeting application, or a wallet that combines every financial provider. It is best understood as a direct channel to Amex account tools. That makes the interface more purposeful, but it also means the app cannot become a central view of unrelated accounts.
There is also a psychological friction point with payments. Seeing a payment control does not mean I should rush through it. I check the selected account, amount, and timing before confirming anything. A mobile screen encourages quick taps, while a payment is one of the moments when slowing down is sensible. The strongest workflow is not simply opening the app and tapping the first available action; it is checking the details, confirming the result, and saving any confirmation information I may need later.
News and Features Related to Amex

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
What I check before blaming the app
When a screen does not load properly, I start with the basics: stable internet access, the latest installed app version, and enough time for the account view to refresh. Switching between weak Wi-Fi and mobile data can produce inconsistent results, so I prefer testing one reliable connection rather than repeatedly reopening the app. I also close other demanding apps if the phone is running slowly, then reopen Amex once instead of forcing a long chain of restarts.
The current version is 7.32.2, and keeping the installed version current is a sensible first step whenever a screen behaves differently from normal. Updates can change how a login or account view behaves, so I would read the update screen before assuming that a familiar button has disappeared permanently. If the app is already current, reinstalling should not be my first reaction; I would first make sure I can still access the account through a trusted alternative and understand what information I may need to sign in again.
Don't want to read the full review?
Phone settings matter too. Automatic date and time are worth checking because an incorrect device clock can interfere with secure sign-in or make recent activity appear out of sequence. I also make sure the phone is not in an unusually restrictive network mode. These are simple checks, but they are more useful than repeatedly tapping a frozen screen. The goal is to separate a local device issue from an account or service issue.
For first-time setup, I would use the official app-store entry, confirm that the developer shown is American Express, and avoid installing a similarly named imitation. The app is free, is rated for Everyone, and has been available since December 2, 2010. Those details make it easy to identify, but I still treat any request for unusual personal information outside the normal sign-in flow with caution.
Screenshots
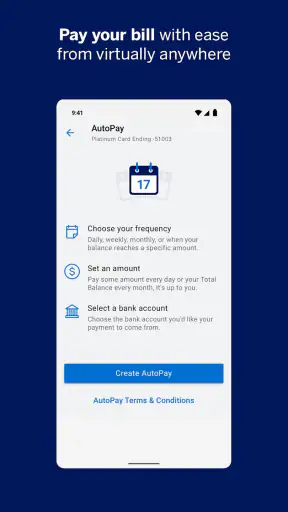
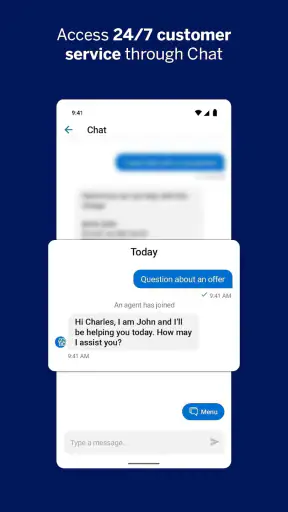
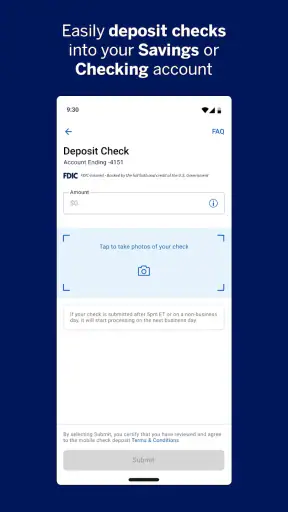
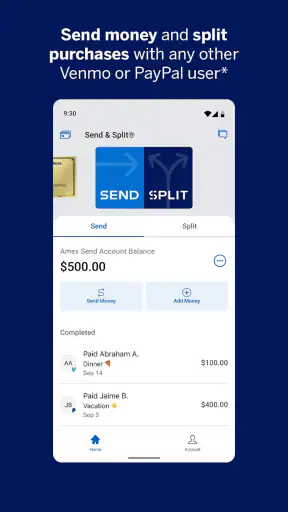
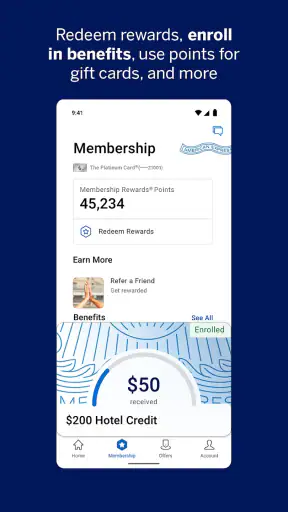
I would also prepare for the practical details of mobile access. A secure screen lock on the phone is important because the device may provide access to account information. I avoid using a public computer or an unfamiliar network for account recovery, and I do not share verification codes with anyone who contacts me unexpectedly. These habits are not special features of the app; they are sensible safeguards for any application that displays financial information.
A setup routine that avoids unnecessary trouble
My preferred setup is deliberately boring. I install the official application, open it on a dependable connection, sign in without rushing, and confirm that the account information shown matches what I expect. I then look through the main areas for the tasks I am likely to use, such as checking the balance, making a payment, and reviewing rewards. Doing this before an urgent payment day gives me time to understand the navigation while nothing is at stake.
I would not test a payment with a random amount simply to see how the process works. Instead, I learn the sequence by opening the payment area, reviewing the available choices, and leaving before confirmation if I am only exploring. This is a useful distinction: learning the interface is safe, while submitting an unnecessary financial action creates avoidable consequences.
Notifications and device behavior can also shape the experience. If I expect an important update, I check whether the phone is silencing notifications or restricting the app in the background. I do not assume that a missing notification means the underlying account action failed. I open the account directly and look for a visible status before taking another action. That habit prevents duplicate attempts, especially with payments.
One practical tip is to keep a simple record of the last successful action when troubleshooting. For example, I might note that the balance was visible in the morning but the payment page would not open later. That is more useful than saying only that “the app stopped working.” Precise observations help me decide whether to retry later, check the account elsewhere, or contact American Express support.
Recovering a disrupted payment or account workflow
If a payment process is interrupted, I stop before submitting it again. I first check whether the app shows a confirmation, pending state, or updated account activity. If the screen closed unexpectedly, I verify through the account view rather than relying on memory. The important principle is to avoid duplicate actions when the first attempt may have reached the service even though the phone did not display the final result.
When the account view is stale, I refresh it once after confirming the connection. If that does not help, I close and reopen the app, then compare what I see with another trusted way of accessing the account if one is available to me. I would not keep refreshing for several minutes or repeatedly submit forms. Repetition can make it harder to tell which action actually succeeded.
Rewards require a slightly different mindset. I treat the rewards area as a place to review available information, not as a reason to make an impulsive purchase or redemption choice. If the displayed total changes later than expected, I check the transaction history and allow for the possibility that recent activity has not appeared immediately. The useful workflow is to compare the relevant transaction with the rewards view and keep the timing clear, rather than assuming every delay is an error.
For login trouble, I begin with the least disruptive steps: confirm the username and password carefully, check the connection, and use the account-recovery route presented by the official service if needed. I avoid trying many variations in quick succession. If the phone has autofilled an old password, I clear that assumption and enter the current details deliberately. A password manager can help with accuracy, provided it is one I trust and the device is secured.
Reinstalling can sometimes clear a damaged local installation, but I see it as a later troubleshooting step rather than a universal cure. Before doing it, I make sure I know how I will sign in again and that I am not depending on the app as my only way to reach the account. Reinstallation may remove local convenience, but it does not fix an incorrect account credential, a service interruption, or a restriction on the account itself.
There is a useful recovery rule for every financial action: one attempt, one verification, then a decision. I submit once, inspect the result, and only retry when I have a clear reason to believe the action did not go through. This is one of the less obvious advantages of using the app carefully. The application can make account management faster, but the user still has to provide the pause that prevents mistakes.
When the phone is not the cause
Some problems sit outside the application. A payment may be affected by the account, the selected funding source, or timing rather than by the mobile interface. A missing transaction may reflect processing rather than a display failure. If the same issue appears after a careful retry on a reliable connection and through another trusted access method, I stop treating it as a phone problem.
This is also where support becomes more useful than experimentation. I would contact American Express through an official channel when an account action remains unclear, when access cannot be restored, or when a financial status needs authoritative confirmation. I would describe the exact screen, the action attempted, and whether any confirmation appeared. I would never include a password or verification code in an unsolicited message.
The app’s popularity gives some context for confidence, though it should not replace careful use. It has an average rating of 4.8 from around one hundred thousand ratings, with roughly fifteen thousand written reviews, and more than ten million installs. Those figures suggest that many customers find it dependable, but they do not guarantee that every account, phone, or network will behave identically. A high rating tells me the core experience works well for many people; it does not remove the need to verify a payment.
Compared with using the American Express website in a browser, the app feels better suited to quick checks during the day. I do not need to find a computer just to view a balance or inspect rewards. The browser remains a useful fallback when the app is unavailable, when I want a larger screen, or when I am already managing several accounts in one session. The choice is less about which option is universally superior and more about whether I need speed or a broader workspace.
Compared with a general budgeting app, Amex offers a more direct relationship with the American Express account. A budgeting tool may be better for combining spending from different institutions, setting a household plan, or viewing a wider financial picture. The Amex app is the better choice when the task is specifically tied to the Amex account and I want fewer layers between me and that task. I would use both categories only if I genuinely needed both functions, not because one should replace the other.
Who will get the most from it
I think the app is a strong fit for an existing American Express customer who checks account activity away from a desk, makes payments from a phone, or wants a convenient way to review rewards. It is especially practical for someone who travels between home, work, and errands and does not want to wait until a laptop is available. The free price removes a common barrier to trying it, and the Everyone age rating makes it broadly accessible, although responsible account use still depends on the individual.
A realistic everyday example is a lunch-break check before a planned payment. I open the app, review the current account information, enter the payment workflow, and pause to verify every visible detail before confirming. Afterward, I return to the account view to make sure the action has a recognizable status. If the screen fails to update, I do not submit again immediately; I record what happened and verify through another trusted route. That small routine is more valuable than simply knowing where the payment button is.
I would recommend a different option to someone who does not have an American Express account, wants one application for multiple banks, or needs detailed budgeting and spending analysis across providers. I would also choose a browser or larger-screen method for complicated account administration where reading every detail on a phone feels cramped. The mobile app is convenient, but convenience should not force a task into a smaller format than it deserves.
My final view is that Amex succeeds because it stays close to the jobs its customers actually need: account access, payments, and rewards. Its weak points are less about unnecessary decoration and more about the consequences of mobile friction when a login, refresh, or confirmation does not behave as expected. With a current installation, a secure phone, a reliable connection, and a habit of verifying actions instead of repeating them, I find it dependable for everyday account management.
For me, the deciding question is simple: do you want direct mobile access to an American Express account, or are you searching for a complete financial control center? If it is the first, I would confidently try it. If it is the second, I would pair it with another tool or choose a broader alternative. The best way to use this app is as a careful, direct account companion—not as a replacement for every financial service on your phone.
Amex FAQ
What is the Amex app used for?
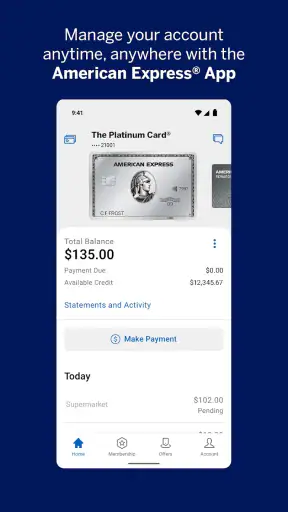
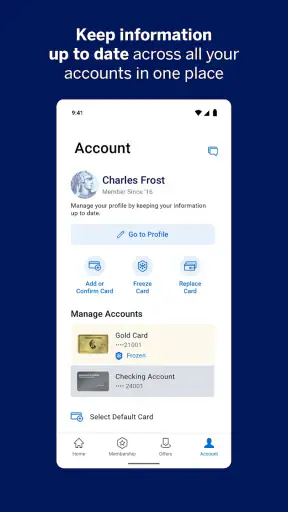
The Amex app is the mobile companion for American Express cardmembers. After signing in, you can review recent and pending transactions, check your available credit, view statements, make payments, manage rewards, and receive account alerts. Depending on your card and country, the app may also provide travel benefits, Amex Offers, customer support, and tools for managing additional cards.
Is the Amex app free to download and use?
Yes, the Amex app is generally free to download from the official Google Play Store or Apple App Store, and American Express does not normally charge a separate fee simply for using the application. However, your card’s annual fee, interest, foreign transaction charges, data costs, and other account-related fees still apply. Availability of features can vary by market and card type.
Can I make payments and manage my Amex account through the app?
In most supported regions, the app lets you make payments, review payment due dates, set up or manage bank accounts, view statements, and monitor your balance or spending activity. Some payment and account-management options depend on your card agreement and location. Before submitting a payment, carefully check the selected funding account, amount, and processing date to avoid delays or returned payments.
Is the Amex app secure to use?
The Amex app includes standard security protections such as encrypted connections, account authentication, device verification, and optional biometric login on compatible phones. Even so, security also depends on your habits. Download the app only from an official store, keep your operating system updated, avoid signing in on public devices, use a strong password, and contact American Express immediately if you notice suspicious activity.
What should I do if I cannot sign in or the app does not work?
If the app will not open or sign-in fails, first check your internet connection, update the app, restart your phone, and confirm that your login details are correct. Temporary maintenance or regional service interruptions can also affect access. Avoid repeatedly entering incorrect credentials, since this may trigger a security lock. If the problem continues, use the official Amex website or contact customer support.












